Earlier this week, in the Bombardier class action, Judge Shira A. Scheindlin denied plaintiff's motion for class certification, finding that the putative class was not entitled to the efficient markets presumption, and as a result, common issues did not predominate the litigation.
A copy of the opinion is available here.
The lead plaintiff in the Bombardier litigation is the Teamsters Local 445 Freight Division Pension Fund and lead counsel is Schoengold Sporn Laitman & Lometti, P.C.
Bombardier, Inc. (TSE: BBD) is a Canadian based manufacturer of regional aircraft, business jets, and rail transportation equipment.
True to form, Judge Scheindlin has provided a thorough analysis of the standards for class certification and a detailed review of the efficient markets theory. I have previously blogged about Judge Scheindlin's thorough securities litigation opinions, here.
Alert readers may recall that earlier in the Bombardier litigation, Judge Scheindlin required the lead plaintiff, after filing an amended complaint that both expanded the class period and added additional securities to the class definition, to issue a new press release and restart the 60 day period for investors to move for appointment as a lead plaintiff.
The PSLRA Nugget had previously blogged about the reopened lead plaintiff period, here.
Daily trivia - Bombardier was founded by Joseph-Armand Bombardier, the inventor of the snowmobile.
Thursday, August 03, 2006


Wednesday, August 02, 2006
The End is Nigh?
Want to have your article reviewed (torn apart) in this blog?
Start with an eye catching title:
His thesis:
Additionally, though he does not define "insiders," a fair interpretation would exclude auditors, underwriters, and others that are proper defendants under the current statutory scheme.
Prof. Booth goes on to state:
A third premise:
Prof. Booth's article appears in the Summer 2006 issue of Regulation, a publication of the Cato Institute. The think tank describes that publication as:
Start with an eye catching title:
The End of Securities Fraud Class Action?Then add a provocative subtitle:
Diversified investors lose more than they gain from securities class actions.That identifies this recent article (also available from SSRN, here) from Prof. Richard A. Booth of the University of Maryland School of Law.
His thesis:
a securities fraud class action should be dismissed for failure to state a claim unless it appears that insiders (including the company itself) have captured gains from trading during the fraud period.I think that the shareholders of any number of scandal ridden companies would take pause with Prof. Booth's central idea.
Only those actions that involve insider trading or the equivalent entail genuine financial harm to the plaintiff class because only those actions involve an extraction of wealth from the public market.
Additionally, though he does not define "insiders," a fair interpretation would exclude auditors, underwriters, and others that are proper defendants under the current statutory scheme.
Prof. Booth goes on to state:
At best, an award from [a securities fraud class action] is nothing more than an expensive rearrangement of wealth from one pocket to another (minus a cut for the lawyers). Diversified investors are equally likely to sell an overpriced stock as to buy one. For diversified investors, gains and losses wash out.This second premise, which is detailed in substantial depth, in effect suggests inflicting a double penalty on investors that are unfortunate enough to have bought artificially inflated shares of a publicly traded company if those shares are part of a portfolio that does NOT contain at least 20 different stocks.
A third premise:
The prospect of payout by the defendant company causes its stock price to fall by more than it otherwise would-even in a perfectly efficient market-and triggers a positive feedback mechanism that has the effect of magnifying the potential payout, sometimes with devastating effects. Indeed, about 30 percent of target companies end up bankrupt.I think this premise is a bit flawed. Companies that are in serious financial trouble already are potentially more likely to resort to conduct that would be considered securities fraud to prop up their stock price. When the truth emerges, the bottom falls out and all sorts of ills may befall that company, including a death spiral into bankruptcy, as institutional investors bail out, debt obligations may be in default, and credit may be cut off. This will happen with or without the filing of a securities fraud class action. Though Ken Lay and Jeff Skilling suggested in their defense a number of other factors that caused Enron to spiral into bankruptcy, they did not blame the class action lawyers.
Prof. Booth's article appears in the Summer 2006 issue of Regulation, a publication of the Cato Institute. The think tank describes that publication as:
the only magazine accessible to the intelligent layman that brings together the latest academic research on the nature and effects of regulation. It offers cutting-edge analysis of the industries that affect your livelihood, covering nearly every sector of the economy, from agriculture and banking to legal reform and transportation.
Tuesday, August 01, 2006
The Scarlet Letter
Yesterday, the law firm of Klafter & Olsen LLP issued a press release announcing the filing of a securities class action against Rambus, Inc. (NASDAQ: RMBS).
Several class actions had already been filed against Rambus, following the May 30 and June 27 announcements that Rambus was investigating (and had found problems with) historical option granting practices at the company.
This was no ordinary press release though. The title screamed:
I'm looking forward to future press releases colorfully announcing the filing of complaints against admitted "GAAP Violators" and "Premature Revenue Recognizers," among others.
The Rambus litigation is pending in the United States District Court for the Northern District of California.
Several class actions had already been filed against Rambus, following the May 30 and June 27 announcements that Rambus was investigating (and had found problems with) historical option granting practices at the company.
This was no ordinary press release though. The title screamed:
Klafter & Olsen LLP Files Class Action Lawsuit Against Options Backdater Rambus, Inc.The choice of language leapt out as most PSLRA press releases tend to sprinkle the word "allegedly" before any factual allegations are presented. As an example, see this earlier press release from another firm that filed a complaint against Rambus. The necessity of the introductory "allegedly" was negated for the Klafter & Olsen release however, as Rambus had already admitted to the conduct with their June 27 announcement.
I'm looking forward to future press releases colorfully announcing the filing of complaints against admitted "GAAP Violators" and "Premature Revenue Recognizers," among others.
The Rambus litigation is pending in the United States District Court for the Northern District of California.
Monday, July 31, 2006
We're Back
Regular posting will now resume.
As my first official act, let me extend a hearty thank you to Kevin LaCroix at The D&O Diary for attempting to compile a comprehensive list (here) of the options backdating related litigation, and to Bruce Carton at Securities Litigation Watch for agreeing to help shoulder the load (here).
The options backdating litigation explosion will almost certainly be the next group of cases that the annual Stanford University /Cornerstone Research, NERA Economic Consulting, and PricewaterhouseCoopers studies exclude from their yearly totals or include with an asterisk, a practice that started back in 2001, with the IPO Allocation cases. The next few years all had their own breed of "atypical" case, except 2005:
2001 - IPO Allocation cases
2002 - Research Analyst cases
2003 - Research Analyst cases and Mutual fund "market-timing" cases
2004 - Mutual fund "market-timing" cases
2005 - ???
2006 - Options backdating cases
When these "atypical" cases have been excluded from the yearly count, the number of new federal securities class action filings has remained fairly steady since the enactment of the PSLRA ten years ago, as explained by Bruce Carton, here.
The "drop" in new case filings that was detailed in a recently released report from Cornerstone Research and the Stanford Law School Securities Class Action Clearinghouse. The report has generated a bit of buzz in the blogosphere, with posts on The 10b-5 Daily here, and The D&O Diary here.
I think a more interesting (and to the best of my knowledge unanswered) question is what happened to the "atypical" cases in 2005?
Thursday, July 20, 2006

Tuesday, July 18, 2006
ECtel Ltd. - Proud Of Their Successful "Vigorous Defense"
ECtel Ltd. (NASDAQ: ECTX) today announced the dismissal of the securities class action lawsuit pending against the company and certain of its directors and officers in the United States District Court for the District of Maryland.
The release quotes ECtel's President and CEO, Eitan Naor, as stating:
Also named as a defendant (and separately announcing their dismissal from the litigation, here) was ECI Telecom Ltd., a major shareholder of ECtel during the class period. Sadly, ECI's press release contains no similar justification, but presumably, they also mounted a vigorous defense.
Judge Roger W. Titus previously appointed Leumi Gemel Ltd. as lead plaintiff and Glancy Binkow & Goldberg LLP and the Law Offices of Jacob Sabo as appointed lead counsel. Cohen, Milstein, Hausfeld & Toll, P.L.L.C. was appointed as liaison counsel.
According to Bank Leumi's 2004 Annual Report, Leumi Gemel Ltd. is a wholly owned subsidiary and:
Thanks to an anonymous reader for sending in the ECtel press release.
The release quotes ECtel's President and CEO, Eitan Naor, as stating:
We're pleased with this confirmation of our earlier statements that we believe this case was filed without merit. This justifies our vigorous defense of this matter.According to their website, one of ECtel's products is known as FraudView and "is the leading and most complete fraud management solution for telecom operators." Hmm, that doesn't sound very good. I wonder if the finance folks at WorldCom were early adopters?
Also named as a defendant (and separately announcing their dismissal from the litigation, here) was ECI Telecom Ltd., a major shareholder of ECtel during the class period. Sadly, ECI's press release contains no similar justification, but presumably, they also mounted a vigorous defense.
Judge Roger W. Titus previously appointed Leumi Gemel Ltd. as lead plaintiff and Glancy Binkow & Goldberg LLP and the Law Offices of Jacob Sabo as appointed lead counsel. Cohen, Milstein, Hausfeld & Toll, P.L.L.C. was appointed as liaison counsel.
According to Bank Leumi's 2004 Annual Report, Leumi Gemel Ltd. is a wholly owned subsidiary and:
manages provident funds for the self-employed, provident funds for salaried employees, central funds for severance pay and a fund for the payment of sick pay and Psagot Ofek [Israel's leading investment house]As an aside, ECI Telecom, Ltd. (NASDAQ: ECIL), the ECtel shareholder named as a defendant in this litigation, settled a prior securities class action alleging that the company fraudulently engaged in a premature revenue recognition scheme, which violated both Generally Accepted Accounting Principles and ECI's own accounting policies. That case settled in 2002 for $21.75 million.
Thanks to an anonymous reader for sending in the ECtel press release.
Monday, July 17, 2006
Bally Total Fitness Securities Class Action Dismissed
Bally Total Fitness Holding Corporation (NYSE: BFT), the largest commercial operator of fitness centers, announced today that the consolidated securities class action pending against the company and several of its current and former officers in the United States District Court of the Northern District of Illinois, was dismissed last week.
The dismissal was without prejudice, and Senior District Judge John F. Grady gave the plaintiffs until August 14, 2006 to file an amended complaint.
A copy of the court's opinion is available here.
The company's former outside auditor, Ernst & Young, LLP, was also a defendant in the litigation. E&Y's motion to dismiss was also granted.
Cosmos Investment Company, LLC was previously appointed the lead plaintiff and Berger & Montague, P.C. and Much Shelist, Freed, Denenberg, Ament & Rubenstein P.C. were appointed lead and liaison counsel, respectively. The Court's order appointing Cosmos as lead plaintiff is available here.
The individual defendants in the litigation were Lee S. Hillman Bally's Chief Executive Officer, President, and Chairman of the Board until December 2002, John W. Dwyer, Bally's former Chief Financial Officer, Executive Vice President, and a member of Bally's Board of Directors, and Paul A. Toback, Bally's current Chief Executive Officer, President, and Chairman of the Board.
Bally's operates more than 400 company owned and franchised facilities in 29 states, Mexico, Canada, Korea, China and the Caribbean.
Options Backdating Revelations - Far from Over
An article in today's New York Times reports that "[m]ore than 2,000 companies appear to have used backdated stock options to sweeten their top executives' pay packages."
The article is based on a newly released study, What Fraction Of Stock Option Grants To Top Executives Have Been Backdated Or Manipulated?, by Professors Erik Lie (Henry B. Tippie College of Business, University of Iowa) and Randall A. Heron (Kelley School of Business, Indiana University - Indianapolis).
According to the Times, the study's authors used information from the Thomson Financial Insider Filing database of insider transactions reported to the Securities and Exchange Commission, to examine nearly 40,000 stock option grants from January 1, 1996 through December 1, 2005 to top executives at more than 7,700 companies.
The article goes on to note:
On that day, revisions to Rules 16a-3, 16a-6 and 16a-8 under the Securities Exchange Act of 1934 took effect, and the SEC began requiring executives to report stock option grants they receive within two business days.
According to the study, after the enactment of the enhanced reporting requirements, "the backdating figure declined to 10 percent of unscheduled grants."
While approximately 5 dozen companies have already disclosed that they: 1) are the targets of government investigations; 2) are the subject of investor lawsuits; or 3) have conducted internal audits involving the practice, this new study estimates:
The article is based on a newly released study, What Fraction Of Stock Option Grants To Top Executives Have Been Backdated Or Manipulated?, by Professors Erik Lie (Henry B. Tippie College of Business, University of Iowa) and Randall A. Heron (Kelley School of Business, Indiana University - Indianapolis).
According to the Times, the study's authors used information from the Thomson Financial Insider Filing database of insider transactions reported to the Securities and Exchange Commission, to examine nearly 40,000 stock option grants from January 1, 1996 through December 1, 2005 to top executives at more than 7,700 companies.
The article goes on to note:
The findings were based on an analysis of whether share values increased or declined after option grant dates. "Half should be negative and half should be positive," said Professor Lie. "That's the underlying logic."The study concluded that before Aug. 29, 2002, 23% of unscheduled grants - as distinguished from grants that companies routinely schedule annually - were backdated.
But the analysis revealed that the distribution was shifted upward.
"This is not random chance. It's something that's manipulated, clearly," said Professor Lie.
On that day, revisions to Rules 16a-3, 16a-6 and 16a-8 under the Securities Exchange Act of 1934 took effect, and the SEC began requiring executives to report stock option grants they receive within two business days.
According to the study, after the enactment of the enhanced reporting requirements, "the backdating figure declined to 10 percent of unscheduled grants."
While approximately 5 dozen companies have already disclosed that they: 1) are the targets of government investigations; 2) are the subject of investor lawsuits; or 3) have conducted internal audits involving the practice, this new study estimates:
that 29.2 percent of companies have used backdated options and 13.6 percent of options granted to top executives from 1996 to 2005 were backdated or otherwise manipulatedIt appears that all of the options backdating taskforces will have their hands full.
Sunday, July 16, 2006
Vigorous Defense, Again
According to news reports here (Austin Business Journal) and here (Austin American-Statesman), a class action lawsuit has been filed in Travis County District Court challenging the proposed acquisition of Encore Medical Corporation (NASDAQ: ENMC) by a subsidiary of Blackstone Capital Partners V L.P.
The American-Statesman article has a quote from Harry L. Zimmerman, Encore's Executive Vice President and General Counsel. Regular readers can guess what Mr. Zimmerman said:
The deal, valued at approximately $870 million, was announced on June 30.
Encore Medical is a diversified orthopedic device company that develops, manufactures and distributes a range of orthopedic devices, including surgical implants, sports medicine equipment and products for orthopedic rehabilitation, pain management and physical therapy.
Blackstone Capital Partners V is one of the world's largest private equity funds, having raised over $15.6 billion in 2006.
The American-Statesman article indicates that Willie C. Briscoe of Provost Umphrey Law Firm LLP is counsel for plaintiff Louis Dudas in the litigation. According to the firm's website:
The American-Statesman article has a quote from Harry L. Zimmerman, Encore's Executive Vice President and General Counsel. Regular readers can guess what Mr. Zimmerman said:
The lawsuit is baseless and without merit, and we will vigorously defend it.If only it was in a press release. . .
The deal, valued at approximately $870 million, was announced on June 30.
Encore Medical is a diversified orthopedic device company that develops, manufactures and distributes a range of orthopedic devices, including surgical implants, sports medicine equipment and products for orthopedic rehabilitation, pain management and physical therapy.
Blackstone Capital Partners V is one of the world's largest private equity funds, having raised over $15.6 billion in 2006.
The American-Statesman article indicates that Willie C. Briscoe of Provost Umphrey Law Firm LLP is counsel for plaintiff Louis Dudas in the litigation. According to the firm's website:
Although the Texas Board of Legal Specialization has certified only 10% of lawyers in Texas, every Senior Partner at Provost Umphrey Law Firm is Board Certified in Personal Injury Trial Law.We can only assume that they will vigorously prosecute the litigation.
Friday, July 14, 2006
Parlux, Part Deux
According to a press release and an 8-K filed by the company this week, the offer to acquire all of the outstanding shares of common stock of Parlux Fragrances, Inc. (NASDAQ: PARL) by the company's CEO, Ilia Lekach, has been withdrawn.
This will likely largely moot the controversy raised in the class and derivative cases discussed in my prior post on Parlux here, so in all likelihood, we will never know if Parlux intended to raise a vigorous defense. I have posted about the vigorous defense phenomenon (and some interesting permutations) here, here, and here.
But our story doesn't end there. According to this post from the WSJ Law Blog:
As an aside, Parlux has posted on their website the following policies:
This will likely largely moot the controversy raised in the class and derivative cases discussed in my prior post on Parlux here, so in all likelihood, we will never know if Parlux intended to raise a vigorous defense. I have posted about the vigorous defense phenomenon (and some interesting permutations) here, here, and here.
But our story doesn't end there. According to this post from the WSJ Law Blog:
Yesterday . . . the Miami Herald reported that six of the seven company directors, including the CEO and CFO, sold Parlux stock in big chunks back in February, when the stock was at or near its all-time high. Since then, the stock price has been cut in halfIf the prior cases did not include allegations relating to this unusual trading foresight (and given the timing of the company's disclosure, they probably did not), it is likely that they will soon be amended. So as one controversy subsides without a vigorous defense, another rises in its place.
As an aside, Parlux has posted on their website the following policies:
- Code of Business Conduct and Ethics (here);
- Code of Ethics For Executive And Financial Officers (here)
- Insider Information And Trading policy (here)
Thursday, July 13, 2006
DHB Settles Class and Derivative Litigation for $40 Million
DHB Industries, Inc. (OTC: DHBT) has announced the settlement of both the securities class action and derivative suits pending in the United States District Court for the Eastern District of New York before Judge Joanna Seybert.
The class action will be settled for $34.9 million in cash, plus 3,184,713 shares of DHB common stock. The derivative action will be settled in consideration of DHB adopting certain corporate governance provisions and paying $300,000, as attorneys' fees and expenses to lead counsel in the derivative action.
According to this Reuters article, "the settlement also includes the removal of Chief Executive David Brooks and other executives from the company's board." It is not clear if these removals are the "corporate governance" changes that result from the settlement of the derivative action.
Brooks was placed on leave earlier this week and according to the Reuters article "is expected to help fund DHB's payments by exercising 3 million warrants. Additionally, DHB can require Brooks to purchase 3 million shares of its common stock to finance the remaining portion of the company's cash settlement."
Lead plaintiffs in the class action are RS Holdings, the NECA-IBEW Pension Trust Fund, and George Baciu. Co-Lead Counsel in the class action are Labaton Sucharow & Rudoff LLP and Lerach Coughlin Stoia Geller Rudman & Robbins LLP.
From a review of the docket, it appears that the settlement comes after the motions to dismiss were fully briefed, but before the Court had ruled on those motions.
DHB is a manufacturer of:
ADDITION: An alert reader (is there any other type?) pointed out this article which dubs Mr. Brooks a "War Profiteer" and indicates that the bat mitzvah Mr. Brooks threw for his daughter in late 2005 cost an estimated $10 million. Flown in by private jet to perform for the affair - Aerosmith, Tom Petty, Don Henley and Joe Walsh, who performed with Fleetwood Mac's Stevie Nicks, Kenny G, 50 Cent, and Ciara. He apparently can afford it, having received more than $70 million in compensation in 2004 alone.
ADDITION: The 10b-5 Daily and the WSJ Law Blog have posts on the settlement, here and here, respectively.
The class action will be settled for $34.9 million in cash, plus 3,184,713 shares of DHB common stock. The derivative action will be settled in consideration of DHB adopting certain corporate governance provisions and paying $300,000, as attorneys' fees and expenses to lead counsel in the derivative action.
According to this Reuters article, "the settlement also includes the removal of Chief Executive David Brooks and other executives from the company's board." It is not clear if these removals are the "corporate governance" changes that result from the settlement of the derivative action.
Brooks was placed on leave earlier this week and according to the Reuters article "is expected to help fund DHB's payments by exercising 3 million warrants. Additionally, DHB can require Brooks to purchase 3 million shares of its common stock to finance the remaining portion of the company's cash settlement."
Lead plaintiffs in the class action are RS Holdings, the NECA-IBEW Pension Trust Fund, and George Baciu. Co-Lead Counsel in the class action are Labaton Sucharow & Rudoff LLP and Lerach Coughlin Stoia Geller Rudman & Robbins LLP.
From a review of the docket, it appears that the settlement comes after the motions to dismiss were fully briefed, but before the Court had ruled on those motions.
DHB is a manufacturer of:
technically advanced bullet and projectile resistant garments, bullet resistant and fragmentation vests, bomb projectile blankets, and related ballistic accessories and technologies for the United States Military and Law Enforcement Agencies.Wearing them instead of selling them might have been a good idea for Mr. Brooks, if you ask me.
ADDITION: An alert reader (is there any other type?) pointed out this article which dubs Mr. Brooks a "War Profiteer" and indicates that the bat mitzvah Mr. Brooks threw for his daughter in late 2005 cost an estimated $10 million. Flown in by private jet to perform for the affair - Aerosmith, Tom Petty, Don Henley and Joe Walsh, who performed with Fleetwood Mac's Stevie Nicks, Kenny G, 50 Cent, and Ciara. He apparently can afford it, having received more than $70 million in compensation in 2004 alone.
ADDITION: The 10b-5 Daily and the WSJ Law Blog have posts on the settlement, here and here, respectively.
Showdown at the Options Backdating Taskforce Corral
According to a post today from WSJ Law Blog, Proskauer Rose LLP has announced the creation of a "Stock Options Task Force." The "special, multi-disciplinary" group of lawyers will work with companies in all matters relating to stock option-related issues.
While it probably wouldn't qualify as a replacement for professional wrestling, now we have the makings of a showdown.
As noted here last month, the plaintiff-side firm of Kahn Gauthier Swick, LLC announced the creation of their own "Options Pricing Investigations Division."
As an aside, I had forgotten that the former "World Wrestling Federation" had been forced to change their name to "World Wrestling Entertainment" after losing an intellectual property case earlier this decade to the World Wildlife Fund.
ADDITION: The D&O Diary also has a post on this showdown.
Wednesday, July 12, 2006
Securities Litigation and Its Lawyers, Perfect Together
Professors Stephen J. Choi (New York University School of Law) and Robert B. Thompson (Vanderbilt University School of Law) have authored a paper Securities Litigation and Its Lawyers: Changes During the First Decade After PSLRA that contains a fairly interesting analysis of the post-PSLRA behavior of class action firms and their institutional investor clients.
Dividing the decade since the PSLRA went into effect, the article bisects the intervening years into two periods:
Their hypothesis:
One last note, though. The article states:
Listen up academia - Mutual funds can and do serve as lead plaintiffs in private securities litigation. You've been warned.
As an aside, Choi and Thompson provide a cogent analysis of one of the potential disincentives for private institutional investors to serve as lead plaintiffs, noting:
Apologies for the title to former New Jersey Governor Tom Kean.
Dividing the decade since the PSLRA went into effect, the article bisects the intervening years into two periods:
the immediate several years right after the enactment of the PSLRA, where law firm behavior likely reflected the need to find a plaintiff or group of plaintiff with the largest financial stake, likely outside the group of institutional investors who initially remained on the sidelines (the "initial" post-PSLRA period)and
the years after the initial several years (2000 and beyond) where plaintiff law firm behavior reflected the need to respond to institutional investors as they came to play a greater role as lead plaintiffs (the "mature" post-PSLRA period).In the former period, the authors found that so-called "top plaintiff law firms" (as determined by settlement values obtained in a sampling of pre- and post-PSLRA cases) were more likely to join together with lower ranked law firms compared with the pre-PSLRA period.
Their hypothesis:
First, the need to create a large group of lead plaintiffs (at least where institutional investors do not act as lead plaintiffs) may lead law firms to join with lower ranked law firms that bring specific lead plaintiffs to the group . . . Second, severe limits on discovery prior to the hearing on the motion to dismiss in the post-PSLRA period increased the importance of diversification as a motive in joining with other law firms. To the extent diversification simply requires other firms willing to help pay the costs of pursuing any particular litigation, we predict that an increased diversification motivation will lead to less discriminate pairing among plaintiffs law firms.There is much more in this draft article, but it will have to wait for another day.
One last note, though. The article states:
There has been a substantial increase in participation of public pension firms, a group that includes well-known public employees' funds such as Calpers, NYCERS and funds related to various unions. At the same time, there has not been any substantial involvement by private investors, such as mutual funds, banks, and insurance companies.This is the same fallacy that I have been on a quixotic quest to banish from the kingdom, as detailed in prior posts here, here, and here.
Listen up academia - Mutual funds can and do serve as lead plaintiffs in private securities litigation. You've been warned.
As an aside, Choi and Thompson provide a cogent analysis of one of the potential disincentives for private institutional investors to serve as lead plaintiffs, noting:
In a world where investment manager performance is regularly measured by relative returns, the possibility of competing managers' free riding on your efforts, or the comparative option of your free riding on other investors operates as a disincentive to participate as a lead investor.Food for thought.
Apologies for the title to former New Jersey Governor Tom Kean.
Tuesday, July 11, 2006
Diversity Training
Late last month, Magistrate Judge Franklin Noel ordered counsel in the UnitedHealth Group Inc. (NYSE: UNH) derivative litigation to provide:
While a number of firms had filed motions seeking appointment as lead counsel, only two groups of firms filed a response to Judge Noel's order. They took slightly different tacks, though.
As an aside, neither response took issue with the use of the term "gender" as opposed to "sex" to describe the information the Court sought. There is a difference, as noted in Encyclopædia Britannica's definition of gender identity. Gender is:
The firms of Chestnut & Cambronne, P.A. and Shapiro Haber & Urmy LLP comprise one group, and represent Jan Brandin, the first plaintiff to file a derivative complaint.
Having been given little guidance by Magistrate Noel as to how inclusive the response was to be, the response filed by Chestnut & Cambronne and Shapiro Haber & Urmy, categorized and specifically identified the attorneys working on the litigation in a number of ways, including their gender and sexual orientation.
The other group to file a response to Magistrate Noel's order, represents the "Pension Fund Group" and includes the firms of Bernstein Litowitz Berger & Grossmann LLP and Grant & Eisenhofer, P.A.
The Pension Fund Group's response included statistical information on all of the employees at both firms as well as a breakdown of the attorneys, noting the number and percentage of each group that "identify themselves as members of racial or ethnic groups commonly described as 'minorities' in the United States." While noting that certain attorneys at Bernstein Litowitz are openly homosexual, the Pension Fund Group's response did not specifically identify those attorneys.
Another interesting note.
Judge Noel's order also requested information on the "makeup of previous steering committees to which [the firms] have been assigned."
Both Bernstein Litowitz and Grant & Eisenhofer indicated in their response that they had not served in any capacity on a "steering committee," as they regularly serve only in the capacity of either lead or co-lead counsel.
For those lead plaintiff junkies out there (all three of you), the Pension Fund Group is composed of:
information concerning the minority and gender membership in your respective law firms, and on the proposed leadership team.and:
a statement advising the Court of any legal-ethical issues raised concerning each individual attorney, and that attorney's law firm in the past ten years.The AP has a story on the Judge Noel's order, here and The Volokh Conspiracy has a post here.
While a number of firms had filed motions seeking appointment as lead counsel, only two groups of firms filed a response to Judge Noel's order. They took slightly different tacks, though.
As an aside, neither response took issue with the use of the term "gender" as opposed to "sex" to describe the information the Court sought. There is a difference, as noted in Encyclopædia Britannica's definition of gender identity. Gender is:
an individual's self-conception as being male or female, as distinguished from actual biological sex. For most persons, gender identity and biological characteristics are the same. There are, however, circumstances in which an individual experiences little or no connection between sex and gender.Back to the business at hand.
The firms of Chestnut & Cambronne, P.A. and Shapiro Haber & Urmy LLP comprise one group, and represent Jan Brandin, the first plaintiff to file a derivative complaint.
Having been given little guidance by Magistrate Noel as to how inclusive the response was to be, the response filed by Chestnut & Cambronne and Shapiro Haber & Urmy, categorized and specifically identified the attorneys working on the litigation in a number of ways, including their gender and sexual orientation.
The other group to file a response to Magistrate Noel's order, represents the "Pension Fund Group" and includes the firms of Bernstein Litowitz Berger & Grossmann LLP and Grant & Eisenhofer, P.A.
The Pension Fund Group's response included statistical information on all of the employees at both firms as well as a breakdown of the attorneys, noting the number and percentage of each group that "identify themselves as members of racial or ethnic groups commonly described as 'minorities' in the United States." While noting that certain attorneys at Bernstein Litowitz are openly homosexual, the Pension Fund Group's response did not specifically identify those attorneys.
Another interesting note.
Judge Noel's order also requested information on the "makeup of previous steering committees to which [the firms] have been assigned."
Both Bernstein Litowitz and Grant & Eisenhofer indicated in their response that they had not served in any capacity on a "steering committee," as they regularly serve only in the capacity of either lead or co-lead counsel.
For those lead plaintiff junkies out there (all three of you), the Pension Fund Group is composed of:
- St. Paul Teachers' Retirement Fund Association
- Public Employees' Retirement System of Ohio
- State Teachers' Retirement System of Ohio
- Public Employees' Retirement System of Mississippi
- Jacksonville Police & Fire Pension Fund
- Louisiana Municipal Police Employees' Retirement System
- Louisiana Sheriffs' Pension & Relief Fund
- Fire & Police Pension Association of Colorado
- The Connecticut Retirement Plans And Trust Funds
Monday, July 10, 2006
Sarbanes-Oxley For Dummies - Really!

While catching up on some long overdue reading, an article in the May 2006 issue of CFO Magazine alerted me to the availability of a laugh-out-loud book title, Sarbanes-Oxley For Dummies.
I was further delighted to see that it is the best selling Sarbanes-Oxley related book on Amazon.
The author, Jill Gilbert Welytok, is a CPA and a practicing attorney, and is the author of a host of other books, including the QuickBooks Bible and The Online Investing Bible.
And Welytok's Amazon profile lists another laugh-out-loud book as one of her favorites - Captain Underpants and the Wrath of the Wicked Wedgie Woman.
All joking aside, her Sarbanes-Oxley book has received excellent reviews at Amazon.
ADDITION - If you intend to buy this book (and I won't judge you), I urge you to visit Amazon through the following link:
This benefits, OBG Cocker Spaniel Rescue, an all-volunteer non-profit animal rescue organization based in Washington DC that is dedicated to the rescue, medical care, rehabilitation and placement by adoption of homeless and/or abandoned cocker spaniels and cocker spaniel mixes to good homes in the Mid-Atlantic region.
We adopted Norm, our 4 year-old cocker spaniel last July through OBG.
Sunday, July 09, 2006
International Institutional Investor "Arms Race"
One of the newer trends in the securities class action arena is a rise in the profile of foreign plaintiffs in US litigation.
Adding to this trend is the increasing emphasis that plaintiff side firms have placed on solidifying their relationships with foreign institutional investors and outside counsel for those investors.
Earlier this year, Labaton Sucharow & Rudoff LLP issued a press release announcing a joint alliance with the TILP Group, a German based firm with offices in Europe and the Middle East that represents private and institutional investors in Germany, Austria, Ireland and Luxembourg. A related announcement by TILP is available here.
The European invasion is being led by Labaton partner Eric J. Belfi, a recent addition to the firm, according to this release.
Other firms certainly represent international clients in securities class actions in the United States, but none have so publicly indicated that they are working together with foreign attorneys to prosecute securities class actions.
For example, Bernstein Litowitz Berger & Grossmann LLP represents the Ontario Teachers' Pension Plan Board in The Williams Cos. securities litigation and the Nortel Corp. securities litigation.
Lerach Coughlin Stoia Geller Rudman & Robbins LLP provides a list on their website of foreign institutional investors they represent, including The London Pensions Fund Authority, and UniSuper - a fund dedicated "exclusively to all who work in Australia's higher education and research sector."
Schiffrin & Barroway, LLP makes their website available in 17 languages (well 15 and two Chinese versions, but I'm not counting) and dedicates a specific part of their website and firm brochure to foreign institutional investors.
Not to be outdone, Cohen, Milstein, Hausfeld & Toll, P.L.L.C. also has an international practice area portion of their website and boasts that they have "affiliated offices in the United Kingdom, Italy, South Africa, Panama, Australia and China." Sadly though, the "International Securities Case" page is "Coming Soon."
Cohen Milstein is also among the growing group of American class action firms that sponsor, speak at, and attend international pension fund summits such as the European Pension Investment Forum and the UK & Irish Pension Summit.
Friday, July 07, 2006
Hypercom Complaint Dismissed (Again)
Today, Hypercom announced the dismissal with prejudice of the Second Consolidated Amended Class Action Complaint filed against the company and its former Chief Financial Officer, John W. Smolak. The litigation was pending in the District of Arizona.
A copy of the second amended complaint is available here.
According to another release from the company, the prior complaint was dismissed with leave to amend, back on January 25, 2006.
Co-lead counsel are Schiffrin & Barroway, LLP and Cohen Milstein Hausfeld & Toll, P.L.L.C.
A copy of the second amended complaint is available here.
According to another release from the company, the prior complaint was dismissed with leave to amend, back on January 25, 2006.
Co-lead counsel are Schiffrin & Barroway, LLP and Cohen Milstein Hausfeld & Toll, P.L.L.C.
Yet Another Press Release Permutation
It appears that someone forgot to send the vigorous defense memo to Parlux Fragrances, Inc.
According to a press release issued by the Fort Lauderdale-based fragrance maker and distributor, the company was recently served with both a shareholder's class action complaint and a derivative complaint, both filed in the Circuit Court of the Seventeenth Judicial Circuit in and for Broward County, Florida. The derivative complaint was filed by the NECA-IBEW Pension Fund.
Both the derivative and class cases relate to a proposal, detailed in Parlux's June 14, 2006 Form 8-K, ) from the company's CEO, Ilia Lekach, to acquire all of the outstanding shares of common stock of Parlux. As noted here, this is not the first time that Lekach has attempted to take the company private.
Parlux's release goes on to state that:
As an aside, it is with some sadness that I note, according to Wikipedia, the National Enquirer has dropped that famous catchphrase.
According to a press release issued by the Fort Lauderdale-based fragrance maker and distributor, the company was recently served with both a shareholder's class action complaint and a derivative complaint, both filed in the Circuit Court of the Seventeenth Judicial Circuit in and for Broward County, Florida. The derivative complaint was filed by the NECA-IBEW Pension Fund.
Both the derivative and class cases relate to a proposal, detailed in Parlux's June 14, 2006 Form 8-K, ) from the company's CEO, Ilia Lekach, to acquire all of the outstanding shares of common stock of Parlux. As noted here, this is not the first time that Lekach has attempted to take the company private.
Parlux's release goes on to state that:
Parlux and the other named defendants have engaged experienced Florida securities counsel and intend to respond to the Class Action and the Derivative Action in a timely manner, but Parlux believes that the Class Action and the Derivative Action are without merit.Be that as it may, enquiring minds want to know if the defendants will mount a vigorous defense?
As an aside, it is with some sadness that I note, according to Wikipedia, the National Enquirer has dropped that famous catchphrase.
Thursday, July 06, 2006
Merrill Lynch Settles Enron Bankruptcy Claims
According to press reports here (AP via Yahoo! Finance) and here (MarketWatch) Merrill Lynch & Co. will pay $29.5 million to settle claims asserted against it by Enron Corp. as part of the so-called MegaClaims litigation in the bankruptcy court.
In addition, Merrill Lynch agreed to drop approximately $74 million of claims that it had asserted in the bankruptcy proceeding against the Enron estate.
Merrill Lynch remains a defendant in the Enron securities class action, currently pending in the Southern District of Texas and set for trial on October 16, 2006.
Friday, June 23, 2006
Presenting the "Preemptive Vigorous Defense" Press Release
Readers have no doubt discerned that securities class action related press releases, in all of their permutations, present a great deal of fodder for my musings.
It appears a new permutation has emerged.
This morning Antigenics Inc. issued a preemptive vigorous defense press release.
The release noted that a purported class action complaint had been filed last week in the United States District Court for the District of New Mexico against the company and its chief executive officer, Garo H. Armen.
Antigenics went on to state:
Of course, they still have some time to get around to it.
The PSLRA states that securities class action plaintiffs, within 20 days of filing a complaint, "shall cause to be published, in a widely circulated national business-oriented publication or wire service, a notice advising members of the purported plaintiff class." See 15 U.S.C. § § 77z-1(a)(3)(A)(i) (Securities Act of 1933), 78u-4(a)(3)(A)(i) (Securities Exchange Act of 1934).
One more thing - isn't issuing a preemptive press release arguably the very discussion of pending litigation that Antigenics indicates it does not do?
It appears a new permutation has emerged.
This morning Antigenics Inc. issued a preemptive vigorous defense press release.
The release noted that a purported class action complaint had been filed last week in the United States District Court for the District of New Mexico against the company and its chief executive officer, Garo H. Armen.
Antigenics went on to state:
The Company believes that the complaint is without merit and plans to vigorously defend against the litigation. The Company's policy is to not discuss pending litigation.Here's the rub - a quick search of Yahoo! Finance, MarketWatch, TheStreet.com, The Motley Fool, reveals that no press release has yet been issued by the firm(s) that filed the complaint.
Of course, they still have some time to get around to it.
The PSLRA states that securities class action plaintiffs, within 20 days of filing a complaint, "shall cause to be published, in a widely circulated national business-oriented publication or wire service, a notice advising members of the purported plaintiff class." See 15 U.S.C. § § 77z-1(a)(3)(A)(i) (Securities Act of 1933), 78u-4(a)(3)(A)(i) (Securities Exchange Act of 1934).
One more thing - isn't issuing a preemptive press release arguably the very discussion of pending litigation that Antigenics indicates it does not do?
Thursday, June 22, 2006
CIBC Settles Global Crossing Related Claims
According to news reports, the Canadian Imperial Bank of Commerce (CIBC), has agreed to settle claims asserted against it in the securities class action filed on behalf of Global Crossing Ltd. and Asia Global Crossing Ltd. shareholders, pending in the Southern District of New York.
While terms of the settlement have not yet been disclosed, sources indicated that the settlement is likely in the range of $20 million.
The lead plaintiffs in the Global Crossing litigation are the Public Employees' Retirement System of Ohio (OPERS) and the State Teachers' Retirement System of Ohio (STRS). Lead counsel is Grant & Eisenhofer P.A.
Remaining defendants include Goldman Sachs and Merrill Lynch, two of Global Crossing's underwriters.
Wednesday, June 21, 2006
More Securities Related Resources
The good folks at the Federal Judicial Center have a number of resources available that may be of use or interest to securities litigators. Two in particular are worth highlighting.
The first is a monograph, Federal Securities Law, authored by Prof. Thomas Lee Hazen. The text is meant as an introduction to the intricacies of the federal securities laws for federal judges.
Though it is a bit dated, having been published in 2003, it is nonetheless a good starting point for one looking for a broad overview of the federal securities laws - and the price (free!) is certainly right.
Prof. Hazen is the Cary C. Boshamer Distinguished Professor of Law at the University of North Carolina at Chapel Hill School of Law.
The second securities class action related resource from the FJC is the fourth edition of the Manual for Complex Litigation. The nearly 800 page tome is aimed at assisting federal trial judges in managing class and complex litigation. For those not wishing to download the entire manual, the table of contents here allows users to download smaller pieces. Though judicial officers are the intended audience, it is nonetheless a helpful resource used often by practitioners. Note that this is not the annotated version available from Thomson - West.
Monday, June 19, 2006
Refco Settlement Derby May Be Heating Up
According to this Dow Jones story (via CattleNetwork.com) a new potential defendant has emerged in the Refco securities class action - the law firm of Mayer, Brown, Rowe & Maw LLP.
That nugget was contained in papers filed last week by the Lead Plaintiffs in support of their motion to modify the PSLRA discovery stay. As noted in that brief, although Mayer Brown is not currently named as a defendant, the firm:
As noted in this National Law Journal article from January, Mayer Brown is actually already involved in the litigation, having been named (along with partner Joseph P. Collins) as a defendant in at least one of the many cases consolidated with the class action, Teachers' Retirement System of Illinois v. Lee, No. 1:05-cv-10403. A copy of the Teachers' Retirement System complaint is available on the Lerach Coughlin website, here.
For those that were wondering, Cattle Network describes itself as "the premier website for any and all information needed in agri-business on a daily basis," with information "on everything from crop insurance to basis to employee benefits to foot rot to the daily boxed beef report." And no, I couldn't find the story on any other public website.
That nugget was contained in papers filed last week by the Lead Plaintiffs in support of their motion to modify the PSLRA discovery stay. As noted in that brief, although Mayer Brown is not currently named as a defendant, the firm:
acknowledges that it is the "Law Firm" described in the Amended Complaint as being responsible for negotiating and documenting the fraudulent "loan" transactions that form the core of the fraud at Refco.Indeed, lead plaintiffs note that as Refco's primary outside law firm for more than a decade, Mayer Brown:
was intimately familiar with Refco's operations and structure and - importantly - prepared some of the documents that lie at the heart of this case.And:
Because documents from Mayer Brown will (as noted above) be pertinent regardless of Mayer Brown's status as a party or non-party to this action, Lead Plaintiffs simply state here that Mayer Brown's confidence that it is insulated from liability is, in a word, optimistic.Sounds like Mayer Brown may be getting in line to join the Refco settlement derby.
As noted in this National Law Journal article from January, Mayer Brown is actually already involved in the litigation, having been named (along with partner Joseph P. Collins) as a defendant in at least one of the many cases consolidated with the class action, Teachers' Retirement System of Illinois v. Lee, No. 1:05-cv-10403. A copy of the Teachers' Retirement System complaint is available on the Lerach Coughlin website, here.
For those that were wondering, Cattle Network describes itself as "the premier website for any and all information needed in agri-business on a daily basis," with information "on everything from crop insurance to basis to employee benefits to foot rot to the daily boxed beef report." And no, I couldn't find the story on any other public website.
Sunday, June 18, 2006
Is it the Bowtie?
Wilson Sonsini Goodrich & Rosati has long been considered one of the giants of the securities class action defense bar. Indeed according to the firm's website:
 Even with the departure of two prominent partners in the last four months, the firm still maintains a very active presence in the field, thanks in large measure to Boris Feldman.
Indeed, I believe Feldman is one of only two members of securities class action defense bar with their own eponymous website - www.borisfeldman.com, complete with a suitably stern picture of Boris with his trademark bowtie.
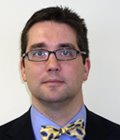 The other member of the defense bar with their own eponymous website - none other than Lyle Roberts, the author of The 10b-5 Daily and the owner of www.lyleroberts.com. Roberts and Feldman were, until recently, partners at Wilson Sonsini, and coincidentally, both are bowtie aficionados.
Roberts joined LeBoeuf, Lamb, Greene & MacRae LLP earlier this month. The firm's announcement can be found here.
Another recently-departed Wilson Sonsini securities litigation partner, Bruce Vanyo, does not have his own website. Vanyo left Wilson Sonsini in February of this year for Kirkland & Ellis, LLP. His stay there was cut short as a result of undiscovered client conflicts, according to this article from The Recorder. Vanyo joined Katten Muchin Rosenman LLP in March. According to uncorroborated sources, Vanyo does not wear bowties, except on formal occasions.
From 1999 to 2004, we have represented more issuers and have completely prevailed in more cases than any other law firm in the country.
 Even with the departure of two prominent partners in the last four months, the firm still maintains a very active presence in the field, thanks in large measure to Boris Feldman.
Indeed, I believe Feldman is one of only two members of securities class action defense bar with their own eponymous website - www.borisfeldman.com, complete with a suitably stern picture of Boris with his trademark bowtie.
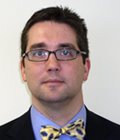 The other member of the defense bar with their own eponymous website - none other than Lyle Roberts, the author of The 10b-5 Daily and the owner of www.lyleroberts.com. Roberts and Feldman were, until recently, partners at Wilson Sonsini, and coincidentally, both are bowtie aficionados.
Roberts joined LeBoeuf, Lamb, Greene & MacRae LLP earlier this month. The firm's announcement can be found here.
Another recently-departed Wilson Sonsini securities litigation partner, Bruce Vanyo, does not have his own website. Vanyo left Wilson Sonsini in February of this year for Kirkland & Ellis, LLP. His stay there was cut short as a result of undiscovered client conflicts, according to this article from The Recorder. Vanyo joined Katten Muchin Rosenman LLP in March. According to uncorroborated sources, Vanyo does not wear bowties, except on formal occasions.
Saturday, June 17, 2006
"Passive Voice Press Releases" and the "Vigorous Defense"
You've seen them discussed separately, but now we have them together. A complaint about a so-called "passive voice press release" and a vigorous defense proclamation by a defendant.
Passive voice press releases are those issued by law firms that have not yet filed a complaint. They typically announce that a securities class action "has been filed." This is distinguished from the active voice releases, which state things such as "[the firm] filed a complaint" or "[the firm] has filed a complaint."
The practice is most often pointed out by one of the firms that filed a complaint, not by the defendant corporation, as we have here.
Earlier this week, InfoSonics Corporation issued a press release, stating:
InfoSonics couldn't resist the lure of the vigorous defense language having read in these pages earlier in the week about a recent successful use of that phrase, and went on to state:
Passive voice press releases are those issued by law firms that have not yet filed a complaint. They typically announce that a securities class action "has been filed." This is distinguished from the active voice releases, which state things such as "[the firm] filed a complaint" or "[the firm] has filed a complaint."
The practice is most often pointed out by one of the firms that filed a complaint, not by the defendant corporation, as we have here.
Earlier this week, InfoSonics Corporation issued a press release, stating:
While at least seven law firms have publicly disseminated press releases over the past few days implying that they have filed lawsuits against InfoSonics Corporation, the Company's preliminary investigation has revealed that two lawsuits seeking class action status have been filed (by three of the firms that issued press releases this week). The remaining four law firms that implied in their press releases that they also filed lawsuits had not done so at the time of their releases and the Company has no knowledge that they have since filed actual lawsuits.This is the classic passive voice press release issue, discussed by The 10b-5 Daily here and here and by Securities Litigation Watch here and here.
InfoSonics couldn't resist the lure of the vigorous defense language having read in these pages earlier in the week about a recent successful use of that phrase, and went on to state:
The Company believes its actions raised in the lawsuits were appropriate and intends to vigorously defend them.Now if only we could find a passive voice press release that indicated the law firm intended to "vigorously pursue" the claims that they have not yet alleged.
Friday, June 16, 2006
More Resources from Weil Gotshal & Manges
Over at Securities Litigation Watch, Bruce Carton has pointed out a helpful resource, the 2005 Securities Litigation Survey, published by Weil, Gotshal & Manges.
Another useful resource is their bi-monthly Business & Securities Litigator. It is available online (with archives stretching back to 1999) or readers may subscribe by e-mailing the firm's webmaster.
Another useful resource is their bi-monthly Business & Securities Litigator. It is available online (with archives stretching back to 1999) or readers may subscribe by e-mailing the firm's webmaster.
The Supremes & SLUSA - Round II (Part II)
The Supreme Court has unanimously ruled to vacate and remand the Seventh Circuit's decision in Kircher v. Putnam Funds Trust, the second Securities Litigation Uniform Standards Act of 1998 (SLUSA) case to be heard by the Court this term.
In an opinion written by Justice David Souter, the Court, held that orders remanding cases that had been removed under SLUSA are non-appealable under 28 U. S. C. § 1447(d). Justice Scalia concurred in part and concurred in the judgment.
ADDITION: The 10b-5 Daily has an analysis of the Court's decision here.
Wednesday, June 14, 2006
"Vigorous Defense" Successful!
According to a press release issued today, Judge William C. Griesbach of the United States District Court of the Western District of Wisconsin has dismissed, in its entirety, the consolidated securities class action pending against Great Wolf Resorts, Inc., and certain of Great Wolf's officers as well as the underwriters of the company's 2004 initial public offering.
Back in November 2005, when the suit was first filed, a Great Wolf spokesperson stated:
Great Wolf is the largest owner, operator and developer in the United States of drive-to family resorts featuring indoor waterparks. You can find a resort near you here.
Lead counsel in the case was Schiffrin & Barroway, LLP.
Back in November 2005, when the suit was first filed, a Great Wolf spokesperson stated:
We believe this suit has no merit, and we intend to vigorously defend it.Readers may recall that both Bruce Carton and I have previously noted the uniform choice of the "vigorous defense" language in corporate press releases. This is the first instance that I can recall where the company's self-professed "vigorous defense" was successful. The wire services have been alerted and are now prepared for the avalanche of these releases that will surely follow.
Great Wolf is the largest owner, operator and developer in the United States of drive-to family resorts featuring indoor waterparks. You can find a resort near you here.
Lead counsel in the case was Schiffrin & Barroway, LLP.
Fighting Cousins?
Over at Securities Litigation Watch, Bruce Carton has a post about an article in The Recorder regarding litigation between counsel in the respective state and federal derivative actions involving Tenet Healthcare.
Counsel in the federal case are Cauley, Bowman, Carney & Williams, LLP. Counsel in the state case include Robbins Umeda & Fink, LLP.
Those two firms have some history. Let's try and untangle the relationship.
First a little background.
Back in the late 1990s, Paul J. Geller and Scott R. Shepherd were partners in what was then known as Shepherd & Geller, LLC. That firm now exists as Shepherd, Finkelman, Miller & Shah, LLC, a 13 attorney firm with offices in 5 states.
S. Gene Cauley and Paul Geller formed a partnership and that firm eventually became Cauley Geller Bowman & Coates, LLP.
The three name partners at Robbins Umeda & Fink were the San Diego office of Cauley Geller prior to 2002, when they left to form their own firm.
In 2003, Sam Rudman left what was then still Milberg Weiss Bershad Hynes & Lerach to join what became Cauley, Geller, Bowman, Coates & Rudman LLP.
We have to take a brief side trip at this point in our story. On May 1, 2004 Milberg Weiss Bershad Hynes & Lerach LLP officially split into Milberg Weiss Bershad & Schulman LLP and what was then known as Lerach Coughlin Stoia & Robbins LLP.
After that, on May 6, 2004, the Cauley Geller firm announced that it would split into two parts - Cauley Bowman Carney & Williams PLLC and Geller Rudman PLLC.
Then on July 1, 2004, Geller Rudman announced that it was merging with what was then Lerach Coughlin Stoia & Robbins LLP to form what is now Lerach Coughlin Stoia Geller Rudman & Robbins LLP.
Did you follow all of that?
Good, then you can play my new game - Six Degrees of Sam Rudman.
Williams Companies Settlement (Part III)
OK folks - This is really the last update.
As noted earlier, the related litigation on behalf of Williams Communications shareholders is still pending.
The class in that case was just certified on Monday by Judge Stephen P. Friot.
Co-lead counsel for the Williams Communications sub-class are Yourman Alexander & Parekh LLP and Milberg Weiss Bershad & Schulman LLP.
As noted previously, a copy of the amended complaint is available here and the opinions on the motions to dismiss are available here.
The lead plaintiff (and one of the class representatives) for the Williams Communications sub-class is Alex Meruelo. With the power of Google, I now know that Mr. Meruelo is the founder of La Pizza Loca, Inc., a fast food pizza restaurant with about 50 franchised and company owned restaurants throughout Southern California. According to Pizza Today Magazine, La Pizza Loca is the 61st largest pizza company in the United States.
Mr. Meruelo is also a member of the board of directors and chairman of the audit committee of Commercial Bank of California and a member of the board of William Lyon Homes one of the nation's largest homebuilders.
As though that was not enough, Mr. Meruelo is also the President and CEO of Meruelo Enterprises, a residential and commercial real estate concern and utility construction contractor, and the President and CEO of Cantamar Property Management.
Tuesday, June 13, 2006
Williams Companies Settlement (Part II)
Seems like everybody was right, sort of.
The litigation is being settled for $311 million. The company, officers and directors, and underwriters (or their insurers) are contributing $290 million and Williams' outside auditors, Ernst & Young, are contributing $21 million.
On August 28, 2004 the Court granted the motions of the Lead Plaintiffs and their counsel to withdraw. The Court then re-opened the lead plaintiff process and set a new deadline for filing lead plaintiff motions. Several parties filed new motions and on January 18, 2005, Chief Judge Sven Erik Holmes appointed the Ontario Teachers' Pension Plan Board and the Arkansas Teacher Retirement System as co-lead plaintiffs and Bernstein Litowitz Berger & Grossmann LLP as lead counsel.
My preliminary research indicates that the Williams settlements dwarf the size of other securities class action settlements in Oklahoma. The largest I have found to date was the $6.2 million settlement in 1997 relating to the demise of Skolnik's Inc., the franchisor of Skolnik's Bagel Bakery restaurants.
Further submissions from readers are, of course, welcome.
Williams Companies Agrees to Settle Class Actions
Houston - we have a disagreement.
According to press reports (Wash. Post), natural gas and pipeline company The Williams Companies, Inc. has agreed to settle the consolidated securities class action pending in the U.S. District Court for the Northern District of Oklahoma for $290 million. The company's press release is here.
According to the company's press release, related litigation on behalf of Williams Communications shareholders is still pending.
Co-lead counsel in that case appeared to be Yourman Alexander & Parekh LLP and Milberg Weiss Bershad & Schulman LLP. A copy of the amended complaint is available here and the opinions on the motions to dismiss are available here.
But according to this release, the litigation is being settled for $311 million. The second release indicates that the Ontario Teachers' Pension Plan Board and the Arkansas Teacher Retirement System are co-lead plaintiffs, and according to the firm's website, Bernstein Litowitz Berger & Grossmann LLP are lead counsel.
As if things were not murky enough, the complaint available on the Bernstein Litowitz website, here, lists HGK Asset Management, Teamsters Local 854 Pension Fund, Local 710 Pension Fund and Local 710 Health and Welfare Fund, and Gary Kosseff as lead plaintiffs and Schoengold Sporn Laitman and Lometti, Kirby McInerney & Squire, LLP, Futterman & Howard, and Murray, Frank & Sailer LLP as co-lead counsel and makes no mention of the Ontario Teachers' Pension Plan Board or the Arkansas Teacher Retirement System.
Looks like we have to dive into PACER to sort this one out. Stay tuned.
As an aside, The Ontario Teachers press release also notes:
This settlement represents the largest securities class action recovery in the history of Oklahoma.Any guesses as to the second largest securities class action in Oklahoma state history?
Cockroaches?
Readers have no doubt noticed that this blog has not commented on the investigation and indictment of Milberg Weiss Bershad & Schulman LLP and name partners David J. Bershad and Steven G. Schulman. That was not merely a myopic oversight, but a reasoned decision.
But now, the gloves are off, and I am compelled to write about one of the more dismaying sideshows, the cheap shot comment.
In a recent article in Forbes magazine, John D. Lovi, the managing partner of Steptoe & Johnson's New York office, and a frequent opponent of Milberg Weiss, when asked if the indictment of the firm spelled the end of Milberg Weiss said:
As noted by the New York State Bar Association's Guidelines on Civility in Litigation:
Let's all agree that name-calling has no place in the profession, even if it is merely being used for illustrative purposes.
Time to get off of my soapbox and return you to your regularly scheduled blog.
But now, the gloves are off, and I am compelled to write about one of the more dismaying sideshows, the cheap shot comment.
In a recent article in Forbes magazine, John D. Lovi, the managing partner of Steptoe & Johnson's New York office, and a frequent opponent of Milberg Weiss, when asked if the indictment of the firm spelled the end of Milberg Weiss said:
They're like cockroaches; they're highly adaptable.The second part of that statement I have no issue with. In fact, the entire comment may have been taken out of context, as Lovi goes on to state:
Unless this firm is destroyed by this investigation and this case, I think they will continue to be a dominant player in the field.But it's the first part of his initial quote that I cannot stomach.
As noted by the New York State Bar Association's Guidelines on Civility in Litigation:
Lawyers should not use vulgar language or make demeaning characterizations of other persons.And:
Lawyers should be mindful of the need to protect the image of the legal profession in the eyes of the public.Similar language is contained in the New York State Bar Association's Code of Professional Responsibility, which state in Canon 7-37:
A lawyer should not make unfair or derogatory personal reference to opposing counsel.I recognize that the guidelines are voluntary, but performing a Google search for lawyer jokes only reinforces the need to be mindful of civility in the profession.
Let's all agree that name-calling has no place in the profession, even if it is merely being used for illustrative purposes.
Time to get off of my soapbox and return you to your regularly scheduled blog.
Monday, June 12, 2006
Chambers USA Ranks Securities Litigation Firms
Chambers and Partners has released the 2006 Guide to America's Leading Lawyers for Business.
Of note, according to this press release, the law firm of Bernstein Litowitz Berger & Grossmann LLP, was given the top ranking in the field of plaintiff securities litigation. The firm's profile is available here. Partners Max W. Berger and John P. ("Sean") Coffey also received the top ranking in that field.
Of note, according to this press release, the law firm of Bernstein Litowitz Berger & Grossmann LLP, was given the top ranking in the field of plaintiff securities litigation. The firm's profile is available here. Partners Max W. Berger and John P. ("Sean") Coffey also received the top ranking in that field.
Does your country have an Enron yet?
 First we had good old regular Enron.
Then we had Parmalat, which many began calling the "Enron of Italy."
Now we have Escala Group, Inc., which is now being called the "Enron of Spain." The Escala Group is the third-largest network of companies in the collectibles market, after Christie's and Sotheby's.
Isn't it time the rest of the world caught up and got their own Enron?
UPDATE: Alert readers have reminded us that competing for the title (presumably with Parmalat) for "Europe's Enron" are Royal Ahold (BusinessWeek article here) and Royal Dutch / Shell Transport n/k/a Royal Dutch Shell plc (Wharton article here).
Also, HIH Insurance Limited has been dubbed the "Enron of Australia" by the BBC, and Elan Corporation, plc, has been dubbed the "Enron of Ireland" notes Gibson Dunn & Crutcher's 2004 Annual Report.
Another reader pointed out that The South Sea Company has been called the "Enron of England." While the second article does indeed use that phrase, it is a bit of a stretch to include it on the list, as the company pre-deceased Enron by about 282 years.
Friday, June 09, 2006
How Many Former Prosecutors Do You Have?
Last week, Lerach Coughlin Stoia Geller Rudman & Robbins LLP announced that John J. Rice, a former Assistant U.S. Attorney had joined the firm. The announcement can be found here.
A review of the firm's biography reveals that Mr. Rice has a lot of company at Lerach Coughlin. The firm has a dozen former federal prosecutors as well as five former state or city prosecutors. For a firm with about 160 lawyers - that works out to a nice ration of 1 out of 10 attorneys being former prosecutors.
While it is not quite the 4 out of 5 dentists that would recommend Trident gum, it is certainly a large percentage for a firm of that size.
Several other attorneys with the firm, including name partners John J. Stoia, Jr. and Samuel H. Rudman, spent time with the United States Securities & Exchange Commission.
For those that just had to know, the dozen former federal prosecutors are:
- X. Jay Alvarez
- Patrick J. Coughlin
- Michael J. Dowd
- Daniel Drosman (also a former Manhattan ADA)
- Jonah H. Goldstein
- G. Paul Howes
- Jeffrey W. Lawrence
- John J. Rice
- Scott Saham
- Sanford Svetcov
- Susan G. Taylor
- David W. Mitchell
Wednesday, June 07, 2006
CalPERS appeals dismissal of NYSE suit
According to this article from BusinessWeek, co-lead plaintiffs, the California Public Employees' Retirement System (CalPERS) and Empire Programs, Inc. have appealed the dismissal of their claims against the NYSE last December by Judge Robert Sweet in the In re NYSE Specialists Securities Litigation. Judge Sweet's opinion is available here.
Judge Sweet had ruled that:
As a result of the specialist scandal, all seven NYSE specialist firms were fined by the SEC. The exchange itself was also censured by the SEC over its failure to police the specialists. A number of individual former traders have been indicted on fraud charges stemming from the case and two have pleaded guilty.
One interesting sidenote to the litigation. One of the lead plaintiffs, Empire Programs, is currently involved in litigation with Sea Carriers, a now-defunct Connecticut-based trading company over payments to be made as a result of the nearly $250 million in disgorgement and civil penalties paid by the specialist firms to settle litigation with the SEC.
The SEC's Order Approving a Distribution Plan, available here, describes the Empire / Sea Carriers litigation at length.
Judge Sweet had ruled that:
NYSE has absolute immunity with respect to Plaintiffs' Section 6(b), Section 20(a), Section 10(b) fraudulent scheme, and state law fiduciary duty claims, all of which are based on NYSE's failure to adequately monitor the conduct of the Specialist Defendants.According to the article, Plaintiffs are arguing on appeal:
The NYSE steps outside its legitimate regulatory capacity and function when it orchestrates a fraud on investors, and those investors have standing to sue for false statements misrepresenting the very market on which they were induced to trade.CalPERS is represented in the litigation by Lerach Coughlin Stoia Geller Rudman & Robbins LLP while Empire Programs is represented by Lovell Stewart Halebian LLP.
As a result of the specialist scandal, all seven NYSE specialist firms were fined by the SEC. The exchange itself was also censured by the SEC over its failure to police the specialists. A number of individual former traders have been indicted on fraud charges stemming from the case and two have pleaded guilty.
One interesting sidenote to the litigation. One of the lead plaintiffs, Empire Programs, is currently involved in litigation with Sea Carriers, a now-defunct Connecticut-based trading company over payments to be made as a result of the nearly $250 million in disgorgement and civil penalties paid by the specialist firms to settle litigation with the SEC.
The SEC's Order Approving a Distribution Plan, available here, describes the Empire / Sea Carriers litigation at length.
Monday, June 05, 2006
Refco Settlement Derby Begins
And the horses are off...
Today, co-lead counsel in the Refco securities litigation, Bernstein Litowitz Berger & Grossmann LLP and Grant & Eisenhofer, P.A., announced a settlement with BAWAG P.S.K. Group for at least $108 million. A copy of the press release announcing the settlement can be found here.
The settlement was part of BAWAG's attempted global resolution of its potential REFCO related liability. BAWAG also apparently into settlements with the United States Attorney for the Southern District of New York and the Official Committee of Unsecured Creditors in the Refco bankruptcy proceedings.
The settlement with BAWAG comes incredibly early in the litigation - less than four months after lead plaintiffs were appointed and just two months after a consolidated complaint was filed. According to the release, " defendants had until July 10 to submit their motions to dismiss the case."
As mentioned last week by this author, co-lead counsel maintains a website devoted to case developments in the Refco litigation here. The prior post is available here.
Thursday, June 01, 2006
The End Of The Mega Securities Case Website?
In recent years, securities litigation groupies have been able to follow developments in some of the major cases via websites set up by lead counsel. With the WorldCom litigation all but finalized and the Enron litigation substantially settled, it's time to find some new websites to satisfy the securities litigation hunger.
Here is a roundup of the case-specific websites:
WorldCom
The website created by Bernstein Litowitz Berger & Grossmann LLP and Barrack, Rodos & Bacine, co lead counsel in the In re WorldCom Inc., Securities Litigation, is perhaps the most inclusive securities class action case specific website ever created. The site contains copies of virtually every pleading filed by the lead plaintiff, New York State Common Retirement Fund, as well as copies of the vast majority of Judge Cote's opinions.
Enron
There are two Enron case-specific websites worth mentioning. The first, available here is updated by lead counsel, Lerach Coughlin Stoia Geller Rudman & Robbins LLP. The second, available here, is updated by the lead plaintiff, The Regents of the University of California. With a trial date looming in the Fall, my guess is that the settlements will keep piling in, and these sites will stay relatively static.
IPO
The website in the Initial Public Offering Securities Litigation has copies of many of the major briefs filed in the case, as well as copies of the amended complaints filed in each of the several hundred consolidated and coordinated cases.
Mutual Funds
The massive morass of cases that grew out of the late-trading and market-timing mutual fund scandals in 2004 does not appear to have a combined website maintained by any of the attorneys involved in the litigation. The Court has a website with opinions and certain other information here.
Merrill Lynch Analyst (Blodget)
Again, there does not appear to be a combined website maintained by any of the attorneys involved in the litigation. The Court has a website here with opinions and certain other information, though it is rather out of date. Note that these cases have been preliminarily settled, see Merrill Lynch's 8-K here.
Refco
Co-lead counsel, Bernstein Litowitz Berger & Grossmann LLP and Grant & Eisenhofer, P.A., maintain a website here, relating to the precipitous corporate meltdown of Refco, which before its implosion, was one of the world's largest providers of brokerage and clearing services in the international derivatives, currency and futures markets.
Odds and Ends
The other remaining mega-cases that easily spring to mind, Fannie Mae and Parmalat, do not appear to have their own websites, yet.
While the unfolding options-backdating scandal does not have a website yet, it probably soon will. According to a press release issued earlier this week:
There are of course two other excellent sources of securities litigation related filings, Stanford Law School's Securities Class Action Clearinghouse, and an alternative site maintained by Lerach Coughlin Stoia Geller Rudman & Robbins LLP here. These clearinghouses were created by local rules in the Northern District of California, available here, which require the posting to a "Designated Internet Site" of virtually all pleadings filed in securities class action cases in that district.
If any readers are aware of case-specific websites (as opposed to case-specific pages that are part of a law firm's general website) that I have missed, please send them along and I'll update the list.
Here is a roundup of the case-specific websites:
WorldCom
The website created by Bernstein Litowitz Berger & Grossmann LLP and Barrack, Rodos & Bacine, co lead counsel in the In re WorldCom Inc., Securities Litigation, is perhaps the most inclusive securities class action case specific website ever created. The site contains copies of virtually every pleading filed by the lead plaintiff, New York State Common Retirement Fund, as well as copies of the vast majority of Judge Cote's opinions.
Enron
There are two Enron case-specific websites worth mentioning. The first, available here is updated by lead counsel, Lerach Coughlin Stoia Geller Rudman & Robbins LLP. The second, available here, is updated by the lead plaintiff, The Regents of the University of California. With a trial date looming in the Fall, my guess is that the settlements will keep piling in, and these sites will stay relatively static.
IPO
The website in the Initial Public Offering Securities Litigation has copies of many of the major briefs filed in the case, as well as copies of the amended complaints filed in each of the several hundred consolidated and coordinated cases.
Mutual Funds
The massive morass of cases that grew out of the late-trading and market-timing mutual fund scandals in 2004 does not appear to have a combined website maintained by any of the attorneys involved in the litigation. The Court has a website with opinions and certain other information here.
Merrill Lynch Analyst (Blodget)
Again, there does not appear to be a combined website maintained by any of the attorneys involved in the litigation. The Court has a website here with opinions and certain other information, though it is rather out of date. Note that these cases have been preliminarily settled, see Merrill Lynch's 8-K here.
Refco
Co-lead counsel, Bernstein Litowitz Berger & Grossmann LLP and Grant & Eisenhofer, P.A., maintain a website here, relating to the precipitous corporate meltdown of Refco, which before its implosion, was one of the world's largest providers of brokerage and clearing services in the international derivatives, currency and futures markets.
Odds and Ends
The other remaining mega-cases that easily spring to mind, Fannie Mae and Parmalat, do not appear to have their own websites, yet.
While the unfolding options-backdating scandal does not have a website yet, it probably soon will. According to a press release issued earlier this week:
Kahn Gauthier Swick, LLC ("KGS") announces the creation of the nation's first privately funded independent Options Pricing Investigations Division, focused on the investigation into the illegal backdating of options grants by US corporations. A growing number of companies are now being investigated by KGS' Options Pricing Investigations Division for improperly manipulating the prices of executive option grants.Thanks to D&O Diary for pointing us to the release.
There are of course two other excellent sources of securities litigation related filings, Stanford Law School's Securities Class Action Clearinghouse, and an alternative site maintained by Lerach Coughlin Stoia Geller Rudman & Robbins LLP here. These clearinghouses were created by local rules in the Northern District of California, available here, which require the posting to a "Designated Internet Site" of virtually all pleadings filed in securities class action cases in that district.
If any readers are aware of case-specific websites (as opposed to case-specific pages that are part of a law firm's general website) that I have missed, please send them along and I'll update the list.
Subscribe to:
Posts (Atom)